Real Estate in the US: Trends, Home Prices & What Buyers Should Know
For many Americans, buying a home is one of the biggest financial decisions they’ll ever make. Whether you’re purchasing your first property, investing for rental income, or building long-term wealth, real estate has become an essential part of personal finance and the US economy.
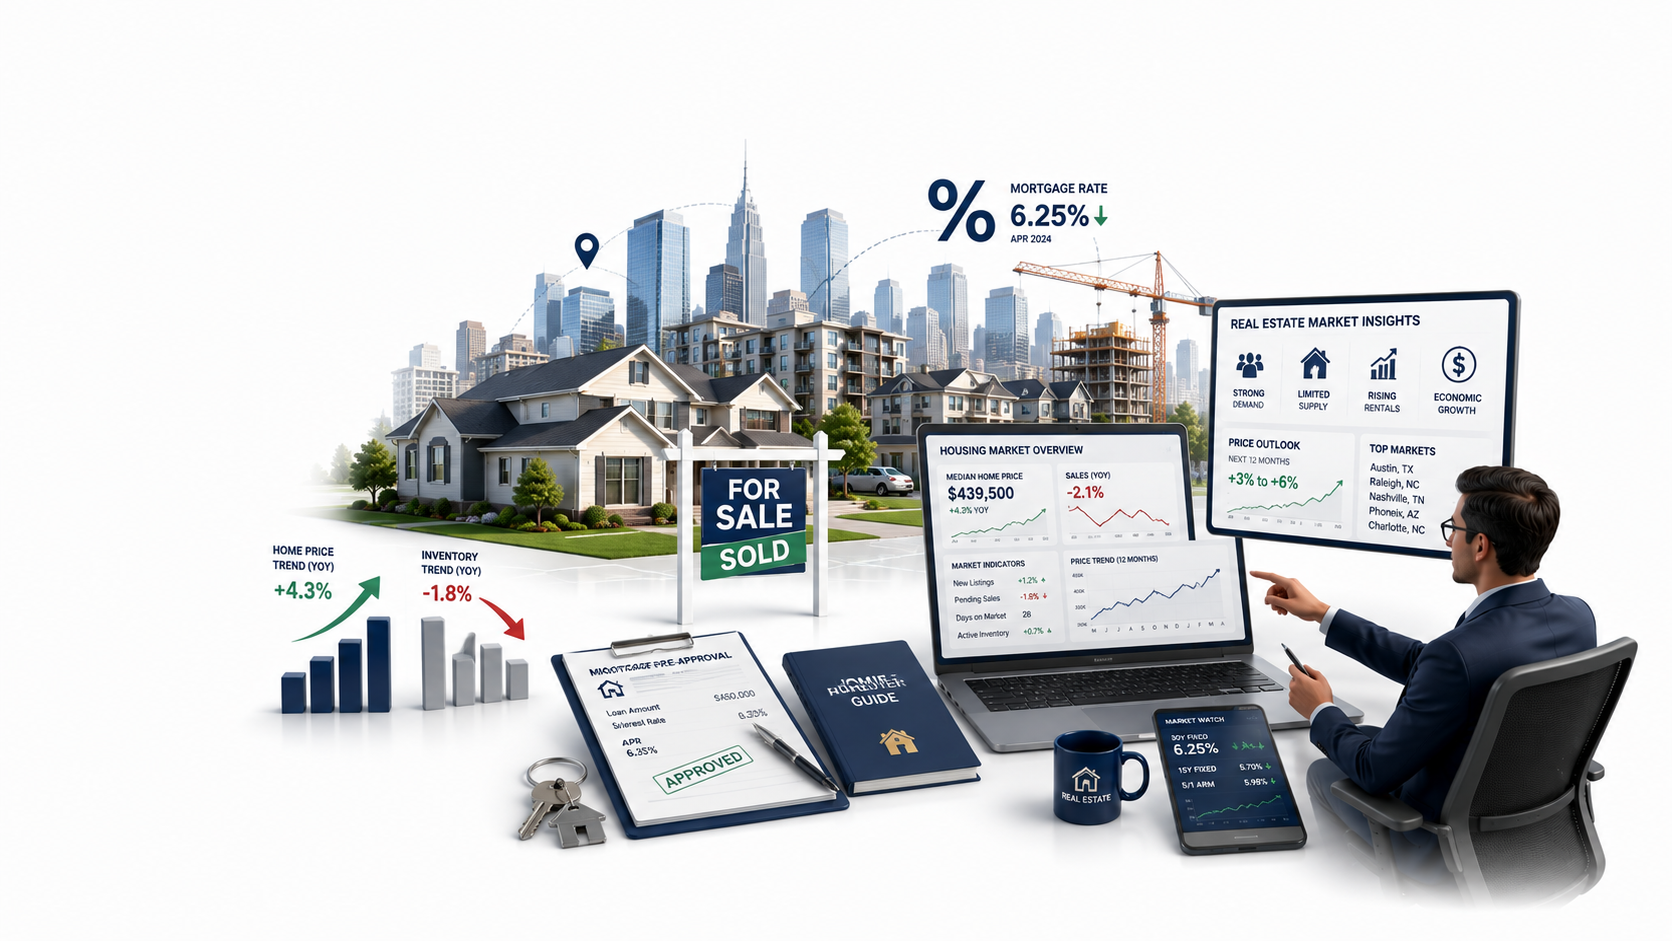
The housing market has undergone significant changes over the past few years. Home prices surged during the pandemic, mortgage rates climbed as the Federal Reserve raised interest rates to combat inflation, and affordability became one of the biggest challenges for prospective buyers.
Despite these headwinds, housing demand has remained relatively resilient in many parts of the country. Limited inventory, population growth, changing lifestyle preferences, and a strong labour market have continued to support property values in several regions.
Understanding how the real estate market works is essential for anyone planning to purchase a home, invest in property, or simply stay informed about one of the world’s largest asset classes.
In this guide, we’ll explain what real estate is, why it matters, the key factors influencing the US housing market, how mortgage rates affect home prices, and what buyers should consider before making one of the biggest financial commitments of their lives.
Financial Planning for Young Professionals
Buying a home is one of the biggest milestones in financial planning for young professionals, often requiring years of disciplined saving and careful budgeting.
What Is Real Estate?
Real estate refers to land and any permanent structures attached to it, including homes, apartments, office buildings, warehouses, shopping centres, and industrial facilities. Unlike movable assets such as vehicles or furniture, it is considered immovable property and is one of the world’s most valuable asset classes.
The industry is broadly divided into four main categories.
Residential Properties
Residential properties are designed for people to live in and include:
- Single-family homes
- Apartments
- Condominiums
- Townhouses
- Duplexes
For most households, owning a home represents both a place to live and a long-term financial asset.
Commercial Properties
Commercial properties are primarily used for business purposes and include:
- Office buildings
- Shopping centres
- Retail stores
- Hotels
- Restaurants
These properties typically generate income through lease agreements and are widely owned by businesses, investment firms, and institutional investors.
Industrial Properties
Industrial properties support manufacturing, production, logistics, and storage activities.
Examples include:
- Warehouses
- Distribution centres
- Manufacturing facilities
- Logistics parks
The rapid growth of e-commerce has significantly increased demand for warehouses and distribution centres across the United States.
Land
This category includes undeveloped land, agricultural land, and plots intended for future residential or commercial development.
Land values are influenced by factors such as location, zoning regulations, infrastructure, and future development potential.
Why Does Real Estate Matter?
Beyond providing housing, real estate is one of the largest contributors to the US economy. Home construction, mortgage lending, brokerage services, property management, insurance, and home improvement collectively support millions of jobs and contribute significantly to economic activity.
For individuals and families, owning property is often the largest component of personal wealth. As homeowners repay their mortgages and property values appreciate over time, they build home equity, strengthening their long-term financial position.
The housing market also serves as an important indicator of economic health. Rising property values can boost consumer confidence and spending, while a slowdown may affect construction activity, lending, and household consumption.
Because of its close relationship with employment, interest rates, inflation, and consumer spending, policymakers, investors, and economists closely monitor developments in this sector.
What Drives the US Housing Market?
Property prices don’t move because of a single event. Instead, they’re influenced by several economic and demographic factors that shape both demand and supply.
Housing Supply
One of the biggest influences on home prices is the availability of homes for sale.
When there are fewer homes on the market than the number of buyers looking to purchase, competition increases, often pushing prices higher. Conversely, a larger inventory can ease price pressures by giving buyers more options.
Many US cities continue to face supply constraints due to years of underbuilding, zoning restrictions, rising construction costs, and shortages of skilled labour.
Mortgage Rates
Mortgage rates play a critical role in housing affordability.
When borrowing costs rise, monthly mortgage payments increase, reducing the purchasing power of prospective buyers. Lower mortgage rates generally improve affordability and encourage housing demand, while higher rates can slow transaction activity as buyers reassess their budgets.
Employment and Income Growth
A healthy labour market supports housing demand because more people have stable incomes that allow them to qualify for mortgages.
Steady wage growth and strong employment typically improve consumer confidence, encouraging households to purchase homes or upgrade to larger properties.
Population Growth and Household Formation
Demographic trends also shape housing demand.
Young adults entering the workforce, growing families, migration between states, and new household formation all influence the need for housing. Regions experiencing strong job creation often attract new residents, increasing demand for homes.
Inflation
Inflation affects the housing market in multiple ways.
Higher material and labour costs increase the expense of constructing new homes, while inflation also influences interest rates, which directly affect mortgage affordability.
As a result, inflation can influence both the supply of new housing and the purchasing power of prospective buyers.
Why Are Home Prices Still High?
One of the biggest questions buyers continue to ask is: If mortgage rates are high, why haven’t home prices fallen significantly?
In a typical market, higher borrowing costs reduce demand, which can place downward pressure on prices. However, the US housing market has behaved differently due to several unique factors.
Limited Housing Inventory
The most significant reason is the shortage of available homes.
Many homeowners secured mortgages during periods of historically low interest rates. Selling their homes today would often mean purchasing another property with a much higher mortgage rate. As a result, many owners have chosen to stay put rather than sell, reducing the number of homes entering the market.
With fewer properties available, competition among buyers remains strong, supporting home prices despite higher financing costs.
Higher Construction Costs
Building a new home has become more expensive.
Developers continue to face higher costs for:
- Construction materials
- Skilled labour
- Land acquisition
- Insurance
- Regulatory compliance
These increased costs make it difficult to significantly reduce prices for newly built homes, limiting additional housing supply.
Strong Employment
The US labour market has remained relatively resilient, with many households continuing to benefit from stable employment and wage growth.
When people feel financially secure, they are generally more willing to purchase homes, helping sustain demand even during periods of higher interest rates.
Population Growth and Migration
Population growth and changing migration patterns continue to shape housing demand.
Some states have experienced significant population inflows as people relocate for employment opportunities, lower taxes, lifestyle preferences, or warmer climates. This increased demand has supported property values in several metropolitan areas, even while other regions have experienced slower activity.
The result is that housing performance varies considerably from one city or state to another, making local market conditions just as important as national trends.
How Mortgage Rates Affect the Housing Market
Mortgage rates are among the most influential factors affecting housing affordability.
When interest rates increase, the monthly repayment on a home loan also rises. Even if the purchase price of a property remains unchanged, higher borrowing costs reduce the amount many buyers can comfortably afford.
For example, a modest increase in mortgage rates can raise monthly repayments by hundreds of dollars over the life of a loan. This often leads some buyers to postpone purchasing a home, reduce their budget, or explore smaller properties.
Lower mortgage rates generally have the opposite effect. Borrowing becomes more affordable, encouraging more buyers to enter the market and increasing competition for available homes.
However, mortgage rates are only one part of the equation.
If housing inventory remains limited, prices may stay relatively stable despite reduced affordability. Likewise, if inventory rises while demand weakens, price growth may slow or even decline in certain markets.
Understanding this relationship helps explain why housing prices don’t always move in the same direction as interest rates.
Is Now a Good Time to Buy a Home?
There is no single answer to this question because every buyer’s financial situation is different.
Rather than trying to perfectly time the market, prospective buyers should evaluate whether purchasing a home aligns with their personal finances and long-term goals.
50/30/20 Budget Rule
Before committing to a mortgage, consider using the 50/30/20 Budget Rule to determine whether your monthly housing costs fit comfortably within your overall financial plan.
Before buying, consider the following questions:
- Can you comfortably afford the monthly mortgage payment?
- Do you have sufficient savings for a down payment and closing costs?
- Do you plan to stay in the property for several years?
- Do you have a stable source of income?
- Have you built an adequate emergency fund?
Buying a home should not place unnecessary strain on your finances. A property may appreciate over time, but homeowners must also account for ongoing costs such as maintenance, property taxes, insurance, utilities, and repairs.
For some households, waiting until their financial position improves may be a better decision than rushing into homeownership simply because market conditions appear favourable.
Common Mistakes First-Time Home Buyers Make
Purchasing a home is exciting, but it is also one of the largest financial commitments most people will ever make. Avoiding common mistakes can help buyers make more informed decisions.
What Is Insurance?
Many first-time buyers focus only on the purchase price and overlook ongoing expenses such as homeowners insurance. Understanding what insurance is can help you better protect one of your biggest financial assets.
Buying More Than You Can Afford
Many buyers focus on the maximum loan amount they qualify for rather than the amount they can comfortably repay each month.
A home should fit your long-term budget, not stretch it.
Ignoring Additional Costs
The purchase price is only part of the total cost of homeownership.
Buyers should also budget for:
- Property taxes
- Homeowners insurance
- Maintenance and repairs
- Utilities
- Closing costs
- Homeowners association (HOA) fees, where applicable
These ongoing expenses can significantly increase the total cost of owning a home.
Skipping a Home Inspection
A professional home inspection can identify structural issues, electrical problems, plumbing defects, roofing concerns, and other costly repairs before completing the purchase.
Skipping this step may result in unexpected expenses after moving in.
Focusing Only on Monthly Payments
Lower monthly payments can sometimes make a loan appear more affordable, but buyers should also consider:
- Total interest paid over the life of the loan
- Loan term
- Interest rate
- Closing costs
Looking only at the monthly payment may not provide a complete picture of the long-term financial commitment.
Not Researching the Neighbourhood
A property’s value depends on more than the home itself.
Factors such as school quality, public transportation, crime rates, employment opportunities, healthcare facilities, and future infrastructure development can all influence both quality of life and long-term property values.
Carefully researching the surrounding area is just as important as evaluating the property itself.
Key Trends Shaping the Future of the US Housing Market
The US housing market continues to evolve as economic conditions, demographic trends, and government policies change over time. While no one can predict exactly how home prices will move, several factors are likely to influence housing activity in the years ahead.
Mortgage Rates
Mortgage rates remain one of the biggest drivers of housing affordability.
Any significant change in interest rates can affect monthly mortgage payments, buyer demand, refinancing activity, and overall housing market sentiment. Prospective buyers should monitor interest rate trends rather than focusing solely on home prices.
Housing Inventory
The availability of homes for sale will continue to play a major role in determining market conditions.
If more homeowners decide to sell or new construction activity increases, buyers may benefit from greater choice and reduced competition. Conversely, limited inventory could continue supporting property prices even if demand moderates.
Population and Migration Trends
Population growth and migration patterns continue to reshape housing demand across the United States.
Some regions have experienced strong demand due to employment opportunities, lower living costs, and favourable business environments, while others have seen slower growth. These regional differences highlight why local market conditions are often just as important as national trends.
Economic Conditions
Employment levels, wage growth, inflation, and consumer confidence all influence housing demand.
A healthy economy generally supports home purchases by improving household income and financial stability. On the other hand, periods of economic uncertainty may encourage some buyers to delay major financial commitments.
Technology and Changing Buyer Preferences
Technology is transforming how people search for, buy, and manage property.
Virtual home tours, online mortgage applications, digital closings, and AI-powered property valuation tools have made the home-buying process more efficient than ever before.
At the same time, changing work patterns have influenced what buyers prioritize. Flexible work arrangements have increased interest in larger homes, dedicated office spaces, and suburban or smaller-city locations for many households.
Should You Invest in Real Estate?
Whether purchasing a primary residence or buying an investment property, real estate should be viewed as a long-term financial commitment rather than a short-term investment.
Like any asset class, property values can rise and fall depending on economic conditions, local supply and demand, interest rates, and broader market sentiment.
Before investing, it’s important to consider:
- Your long-term financial goals.
- Your ability to comfortably afford ongoing ownership costs.
- The location and long-term growth potential of the property.
- Expected maintenance and repair expenses.
- Rental demand, if purchasing an investment property.
- Your overall investment portfolio and diversification strategy.
Owning property can provide financial stability and potential long-term appreciation, but it should be evaluated alongside other investments such as stocks, bonds, mutual funds, and ETFs. A diversified portfolio can help reduce overall investment risk rather than relying heavily on a single asset class.
Conclusion
The US housing market is influenced by a combination of economic conditions, mortgage rates, housing supply, employment, and demographic trends. Understanding how these factors interact can help buyers and investors make more informed financial decisions instead of reacting to short-term market headlines.
While market conditions continue to evolve, successful property ownership is rarely about perfectly timing the market. Instead, it depends on purchasing a home that aligns with your financial situation, long-term goals, and ability to comfortably manage the ongoing costs of ownership.
For first-time buyers, understanding mortgages, budgeting for additional expenses, researching neighbourhoods, and maintaining realistic expectations are just as important as finding the right property.
Ultimately, real estate remains one of the world’s most important asset classes and continues to play a central role in wealth creation, economic growth, and financial planning. By focusing on affordability, careful research, and long-term objectives, buyers can make more confident decisions regardless of changing market conditions.
Frequently Asked Questions (FAQs)
1. What is real estate?
Real estate refers to land and any permanent structures built on it, including homes, apartments, office buildings, warehouses, and commercial properties. It is considered one of the largest asset classes and plays a vital role in the economy and personal wealth creation.
2. Why is real estate important?
Real estate is important because it provides housing, supports millions of jobs, contributes significantly to economic growth, and helps individuals build long-term wealth through property ownership and home equity.
3. What are the main types of real estate?
The four primary types of real estate are:
- Residential real estate
- Commercial real estate
- Industrial real estate
- Land
Each serves different purposes and attracts different types of buyers and investors.
4. Why are home prices in the US still high?
Home prices remain elevated due to a combination of limited housing supply, higher construction costs, strong demand in many regions, population growth, and homeowners choosing not to sell because they have lower existing mortgage rates.
5. How do mortgage rates affect real estate?
Mortgage rates directly influence housing affordability. Higher interest rates increase monthly loan payments, reducing buyers’ purchasing power, while lower rates generally encourage home buying by making financing more affordable.
6. Is now a good time to buy real estate?
There is no universal answer. The right time to buy real estate depends on factors such as your financial situation, income stability, long-term plans, local market conditions, and your ability to comfortably manage mortgage payments and other ownership costs.
7. What additional costs should homebuyers consider?
In addition to the purchase price, buyers should budget for:
- Down payment
- Closing costs
- Property taxes
- Homeowners insurance
- Maintenance and repairs
- Utilities
- Homeowners Association (HOA) fees, where applicable
These expenses can significantly affect the total cost of homeownership.
8. Is real estate a good long-term investment?
Historically, real estate has been considered a long-term investment that can help build wealth through property appreciation and home equity. However, returns are not guaranteed and depend on factors such as location, market conditions, financing costs, and the overall economy.
9. What factors influence the real estate market?
Several factors affect the real estate market, including:
- Mortgage rates
- Housing supply and demand
- Employment levels
- Inflation
- Population growth
- Household formation
- Government policies
- Local economic conditions
These factors work together to influence home prices and market activity.
10. What mistakes should first-time homebuyers avoid?
Some common mistakes include:
- Buying beyond their budget.
- Ignoring closing costs and maintenance expenses.
- Skipping a professional home inspection.
- Focusing only on monthly mortgage payments.
- Not researching the neighbourhood before purchasing.
Careful planning can help buyers avoid costly financial mistakes.
11. How is residential real estate different from commercial real estate?
Residential real estate includes properties designed for people to live in, such as houses, apartments, and condominiums. Commercial real estate consists of properties used for business purposes, including office buildings, shopping centres, hotels, and retail spaces.
12. What should buyers consider before purchasing real estate?
Before buying real estate, consider:
- Your long-term financial goals.
- Employment and income stability.
- Mortgage affordability.
- Emergency savings.
- Property location.
- Future maintenance costs.
- Overall cost of ownership.
A home purchase should fit comfortably within your budget and align with your long-term plans.
13. Can real estate prices fall?
Yes. Like any asset class, real estate prices can rise or fall depending on economic conditions, housing supply, buyer demand, interest rates, and local market trends. While property values have historically appreciated over long periods in many areas, short-term price movements can vary by region.
14. What is home equity?
Home equity is the difference between your home’s current market value and the outstanding balance on your mortgage. As you repay your loan or as your property’s value increases, your home equity generally grows.
15. How can beginners learn more about real estate?
Beginners should start by understanding the basics of the housing market, mortgage financing, budgeting, property taxes, homeowners insurance, and closing costs. Building this knowledge can help buyers make more informed decisions before purchasing their first property.
Books to understand Real Estate Better
- The Millionaire Real Estate Investor – Buy on Amazon
- Master Commercial Real Estate – Buy on Amazon
- The ABCs of Real Estate Investing – Buy on Amazon